A More Active Market, With Less Inventory
Palm Beach Island's residential market maintained its momentum through the summer months, traditionally a quieter period for real estate activity. Third-quarter sales increased across all three residential segments, while available inventory continued to contract.
The single-family market was particularly active, with transactions more than doubling year over year.
Condominium and co-op sales also increased in both Midtown and the South End, although pricing statistics presented a more nuanced picture. Differences in the mix of properties sold, along with variations in location, condition and building quality, remain important considerations when interpreting quarterly results.
Together, these trends point to a more active market with tighter supply as Palm Beach enters its winter selling season.
Single-Family Homes: Stronger Activity Beyond the Trophy Market
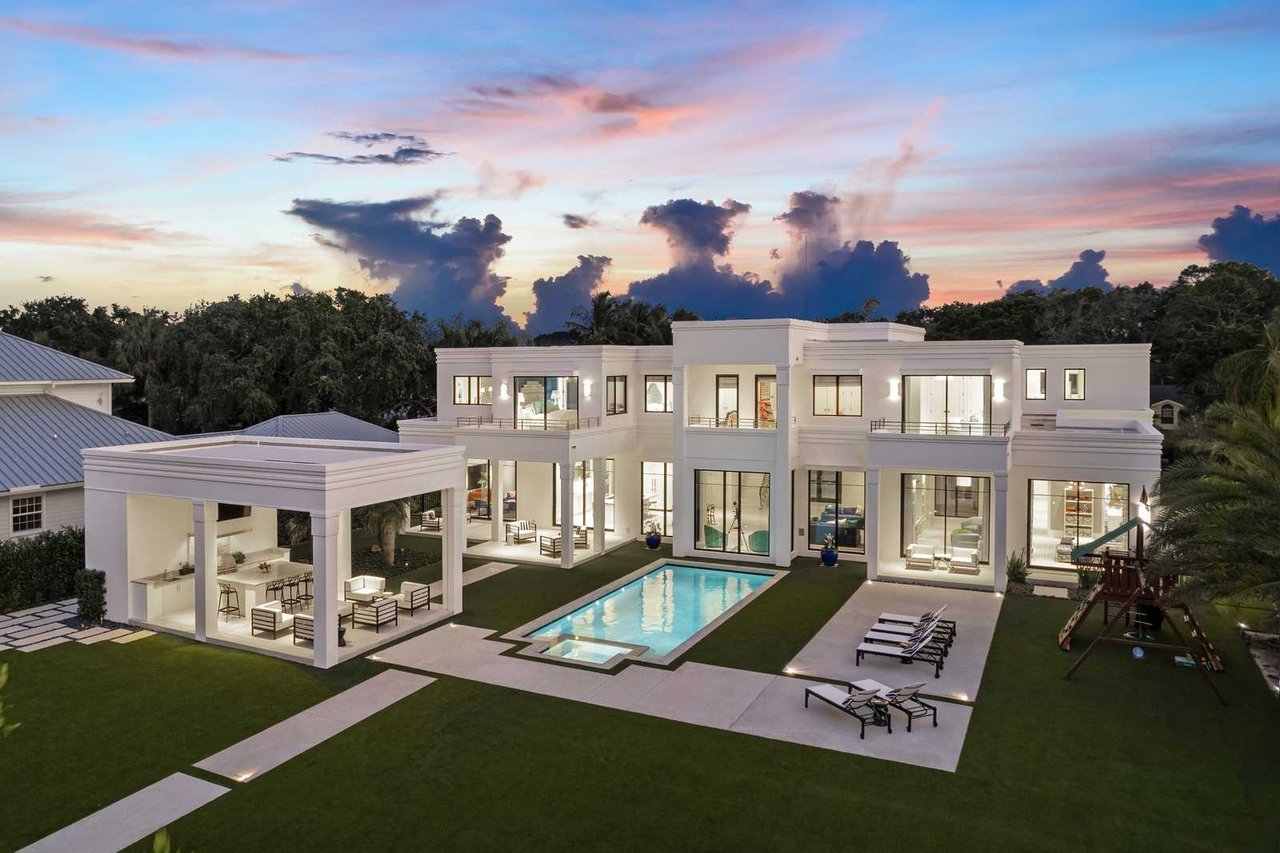
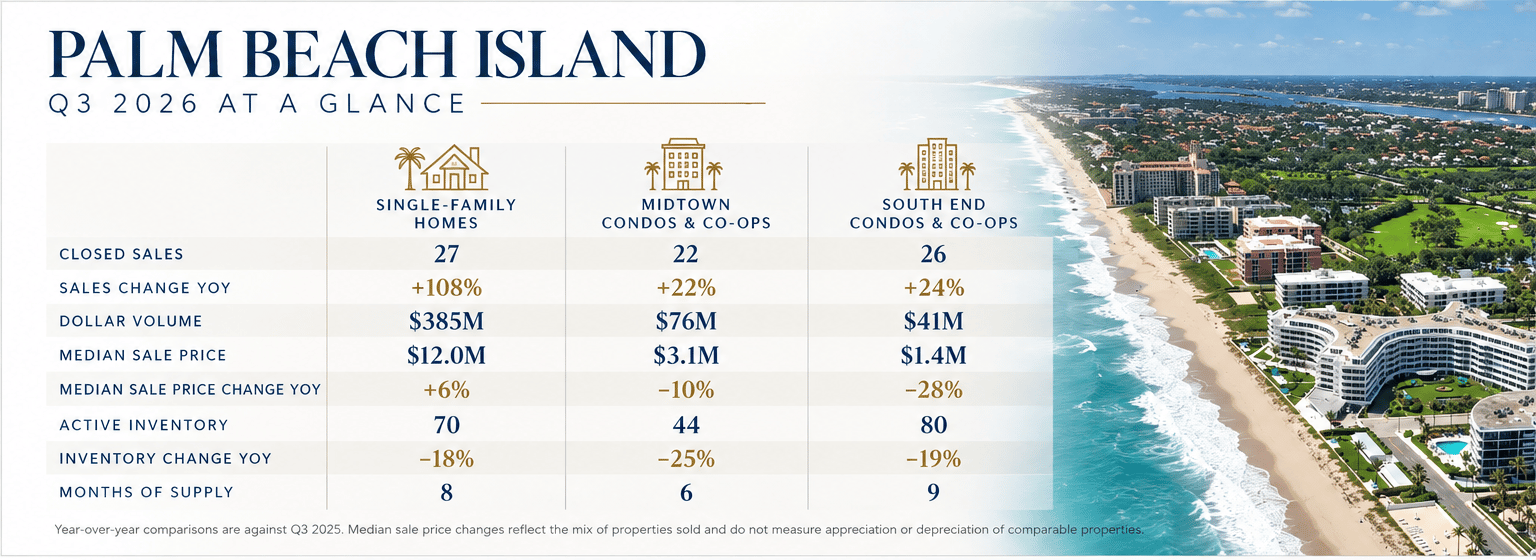
Palm Beach Island's single-family market delivered a particularly strong third quarter, with 27 closed sales, an increase of 108% year over year. Total dollar volume rose 41% to $385 million, while the median sale price increased 6% to $12 million.
The average sale price declined 32% to $14.3 million, reflecting a different mix of transactions than a year earlier. In Q3 2025, the highest reported sale was an $86.5 million off-market transaction, compared with a high of $40 million in Q3 2026. In a market with relatively few transactions, exceptional trophy sales can have a disproportionate influence on average prices.
More notably, transaction activity broadened considerably. More than twice as many single-family homes changed hands, with a higher median sale price and greater overall dollar volume, even without a transaction approaching the prior year's high.
Available inventory declined 18% to 70 properties, representing approximately eight months of supply.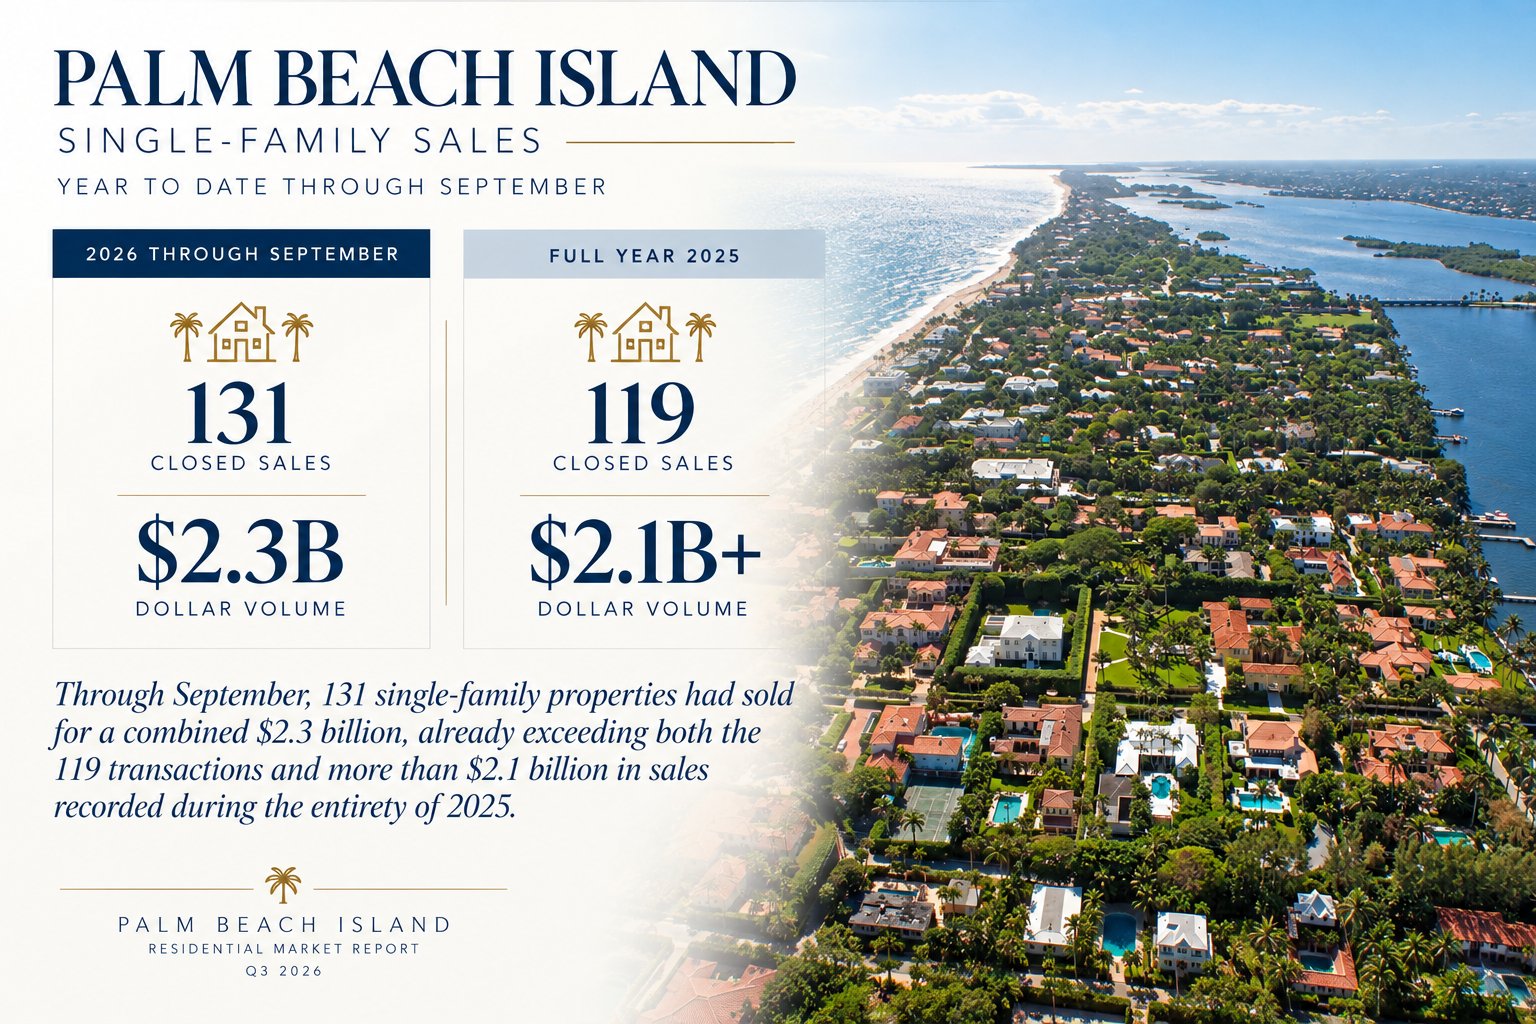
Midtown Condominiums & Co-ops: Stronger Activity, Tighter Inventory
Midtown recorded 22 condominium and co-op transactions during the third quarter, an increase of 22% year over year and the strongest Q3 sales activity since 2021. Available inventory declined 25% to 44 properties, representing approximately six months of supply.
The median sale price declined 10% to $3.1 million, although it remained the second-highest third-quarter median on record. The average sale price fell 28% to $3.5 million, with total dollar volume declining 12% to $76 million.
These pricing measures warrant some context. In a market with relatively few transactions, the mix of properties sold can significantly influence quarterly averages and medians. A separate review of MLS transactions showed increases in both average and median sale prices year over year, illustrating the importance of looking beyond aggregate statistics when evaluating pricing trends.
The combination of increased sales activity and tighter inventory suggests continued demand for Midtown properties. While aggregate pricing measures declined, differences in the mix of residences sold make it difficult to draw conclusions about changes in individual property values.
South End Condominiums & Co-ops: Increased Activity, A Highly Differentiated Market
South End condominium and co-op transactions increased 24% year over year to 26 sales. Available inventory declined 19% to 80 properties, representing approximately nine months of supply.
The median sale price declined 28% to $1.4 million, while the average fell 31% to $1.6 million. Total dollar volume decreased 14% to $41 million.
These aggregate statistics, however, tell only part of the story. The South End encompasses distinctly different condominium markets, including ocean-side and Intracoastal-side buildings, with meaningful differences in property values.
Factors influencing property values include:
· Building age and physical condition
· Financial strength and reserve funding
· Potential assessments
· Individual apartment renovations
Quarterly averages and medians do not capture these distinctions and should not be interpreted as uniform changes in property values.
With approximately nine months of supply, buyers have more choices than in Midtown. The combination of greater inventory and substantial differences among buildings makes property-specific analysis particularly important when evaluating value and identifying opportunities in the South End.
Market Outlook: Looking Ahead
The third quarter sustained the momentum established during the first half of 2026, reinforcing the strength of Palm Beach Island's residential market. With transactions increasing and inventory contracting, attention now turns to whether this pace of activity will continue through year-end.
The single-family market enters the fourth quarter with particularly strong momentum. At September's end, 15 properties were pending in the MLS, representing approximately $528 million in combined asking prices. While these figures do not represent closed sales volume, they suggest a substantial pipeline of potential transactions.
The condominium and co-op markets present a more varied picture. Midtown's relatively limited inventory contrasts with the greater selection available in the South End, where building condition, financial strength and individual property characteristics remain especially important considerations.
Factors Influencing Demand
Beyond current transaction activity, Palm Beach Island continues to benefit from an extraordinary concentration of private wealth and the scarcity of available land. September's Forbes 400 included at least 35 individuals with residential ties to Palm Beach, underscoring the extraordinary concentration of private wealth on the island. Continued investment in financial services, education and healthcare across the surrounding region adds another dimension to Palm Beach's long-term appeal.
Another factor that could influence fourth-quarter demand is Florida's proposed Amendment 3, which would expand homestead property tax exemptions while establishing different eligibility rules based on residency. Individuals who establish Florida residency by December 31, 2026, would be eligible for the expanded benefits upon qualifying for homestead, while those establishing residency in 2027 or later would generally become eligible for the expanded exemption beginning in their fifth year of homestead eligibility. If approved by voters in November, this distinction could encourage some prospective Florida residents to accelerate their relocation decisions before year-end.
As the year draws to a close, the pace of completed transactions and the introduction of new inventory will help determine whether the market's momentum carries into 2027.
Understanding the Market Beyond the Numbers
Palm Beach Island's real estate market is highly differentiated, and broad market statistics are only one part of evaluating an individual property's value and positioning.
Whether you are considering buying, selling or simply assessing your property's position in the current market, I welcome the opportunity to share a more detailed perspective on the factors that matter to your decisions.
Nadine Fite
Luxury Real Estate Advisor | Palm Beach
📧 [email protected]
📱 917.513.9592
🌐 LivePalmBeach.com
📍 Compass Palm Beach
#LivePalmBeach
Market Data & Methodology: Market statistics reflect a third-party compilation of Palm Beach MLS, BeachesMLS, property records and broker-reported transactions for ZIP code 33480. Median and average prices reflect the properties sold during each period and should not be interpreted as measures of appreciation or depreciation for comparable properties.