Third Quarter and Year-to-Date Analysis | Through September 30, 2026
Market Overview: Luxury Demand Extends Across Price Points
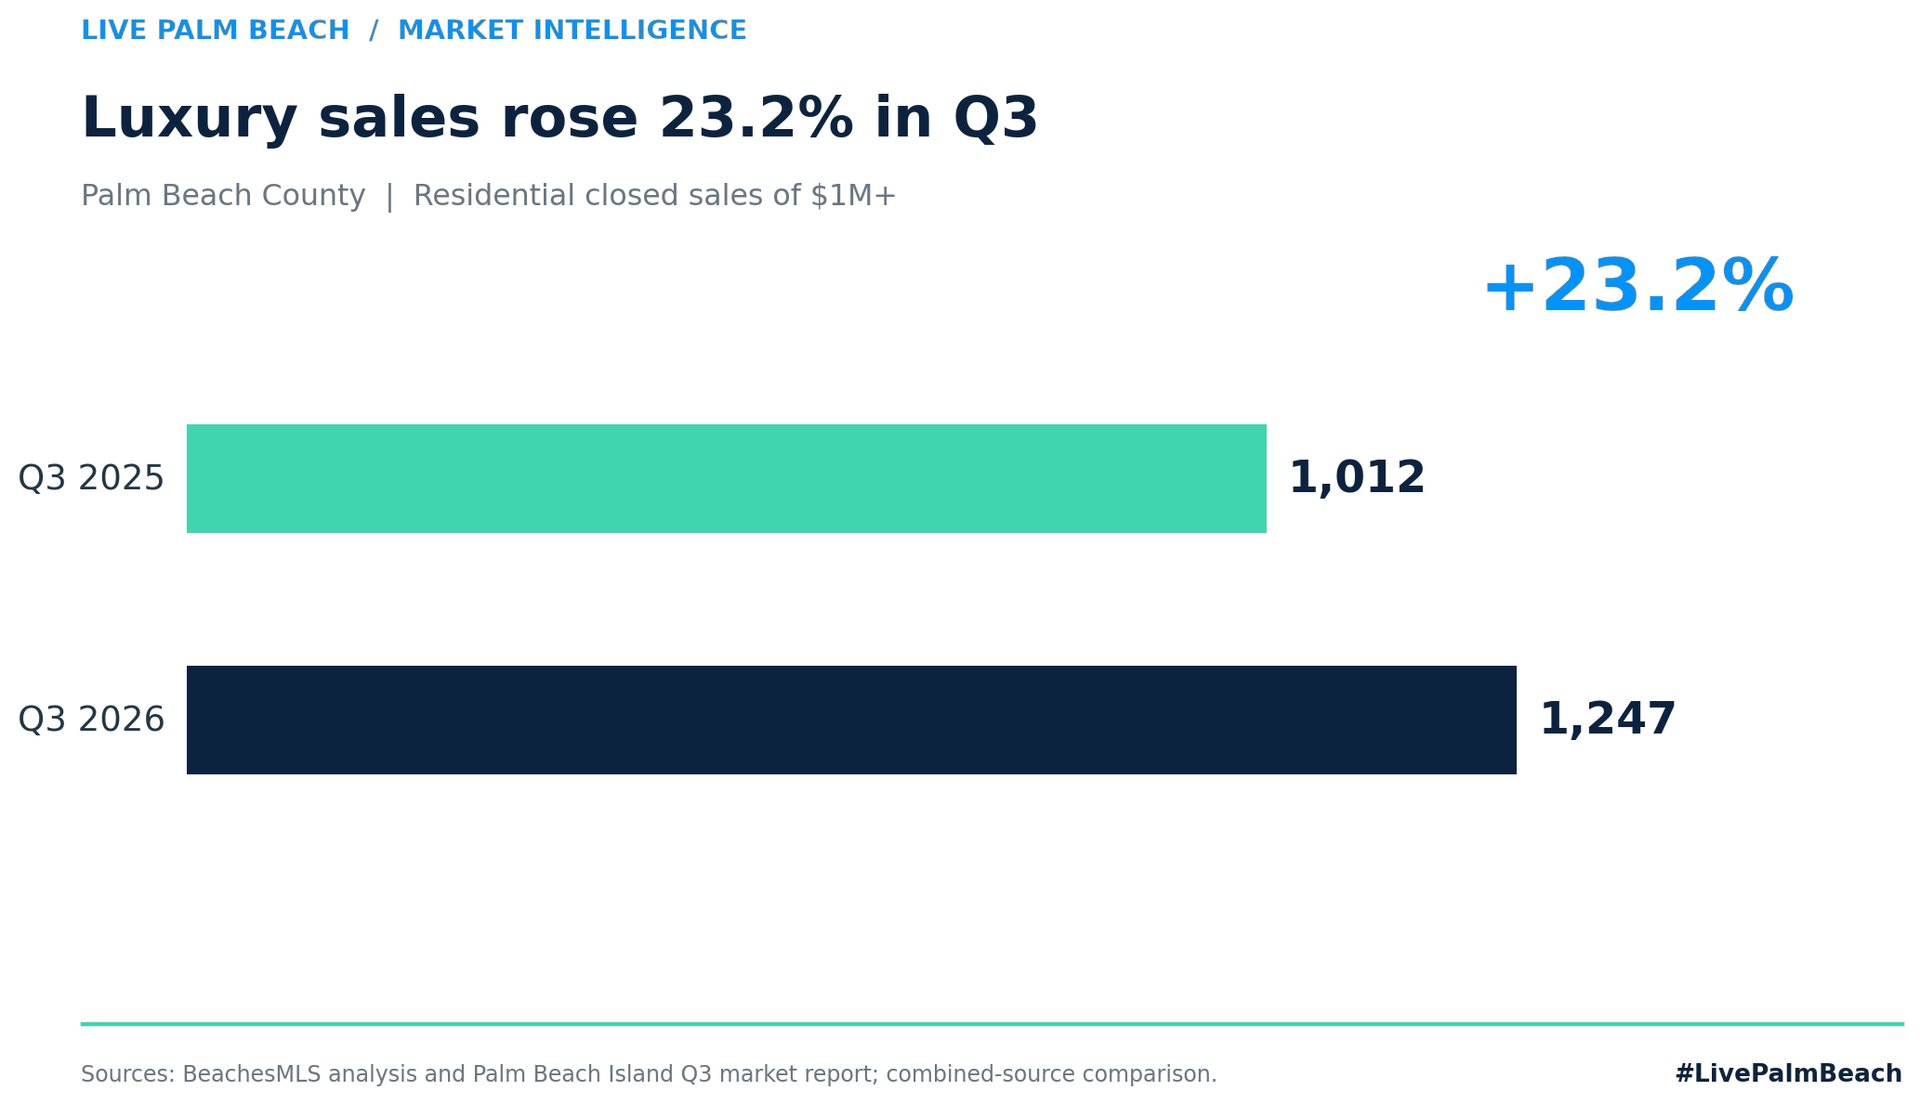
Luxury residential sales accelerated across Palm Beach County in the third quarter of 2026. Transactions of $1 million or more increased 23.2% year over year, from 1,012 to 1,247 sales, including Palm Beach Island.
More importantly, the increase extended well beyond the $1 million entry point. Single-family transactions in the $2 million to $5 million and $5 million to $10 million segments recorded substantial gains during the first nine months of the year.
While extraordinary waterfront estates continue to attract headlines, I believe the more revealing measure of market strength is the number of buyers making significant investments across different price points and communities.
The results also highlight an important distinction between single-family homes and condominiums. Both experienced increased transaction activity, but pricing patterns and competitive conditions varied considerably.
For buyers and sellers, understanding those differences is far more useful than relying on a single countywide statistic.
A Broader View of Luxury Demand
The most interesting development in 2026 is the expansion of transaction activity across higher price categories.
During the first nine months of the year, residential sales of $1 million or more outside Palm Beach Island increased 22.6%, from 3,370 to 4,131 transactions.
Within selected coastal-area communities, single-family sales increased across every major luxury price segment.
Single-Family Sale Price | Jan–Sep 2025 #Sold | Jan–Sep 2026 #Sold | Change |
$1M–under $2M | 923 | 1,108 | +20.0% |
$2M–under $5M | 453 | 610 | +34.7% |
$5M–under $10M | 115 | 159 | +38.3% |
$10M+ | 52 | 71 | +36.5% |
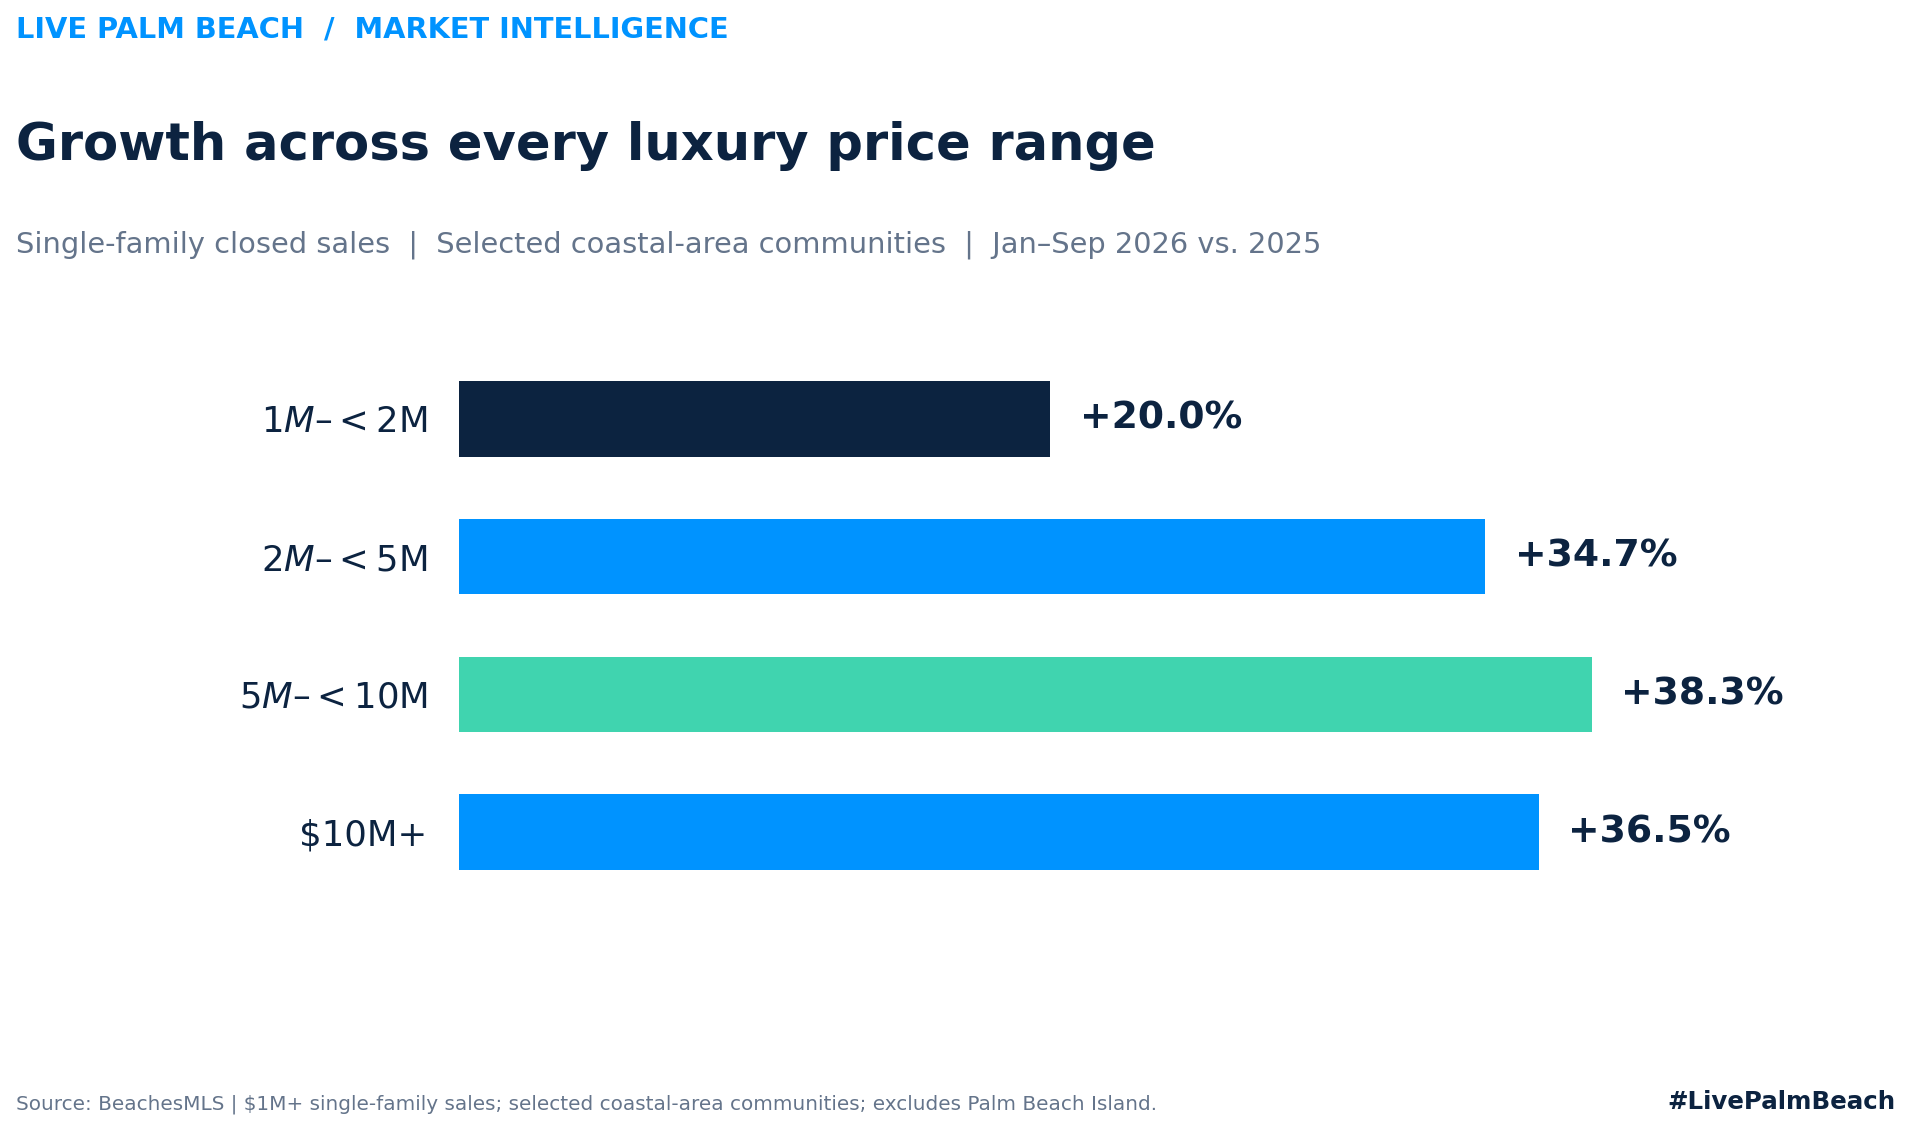
The $5 million to $10 million segment recorded a 38.3% increase, from 115 to 159 transactions. Sales between $2 million and $5 million increased 34.7%.
These are meaningful gains in price ranges that require a substantial financial commitment.
New construction, changing buyer preferences, and properties moving into higher price categories may all be contributing factors. The closed-sales data does not establish the relative influence of each, but it does demonstrate that activity is not concentrated solely at the entry level of the luxury market.
Single-Family Homes: More Sales, Higher Median Prices
Single-family homes were a major contributor to the increase in luxury transactions.
Outside Palm Beach Island, third-quarter sales of homes priced at $1 million or more rose 24.4%, from 814 to 1,013 transactions. The median sale price increased 9.4%, from $1.6 million to $1.75 million.
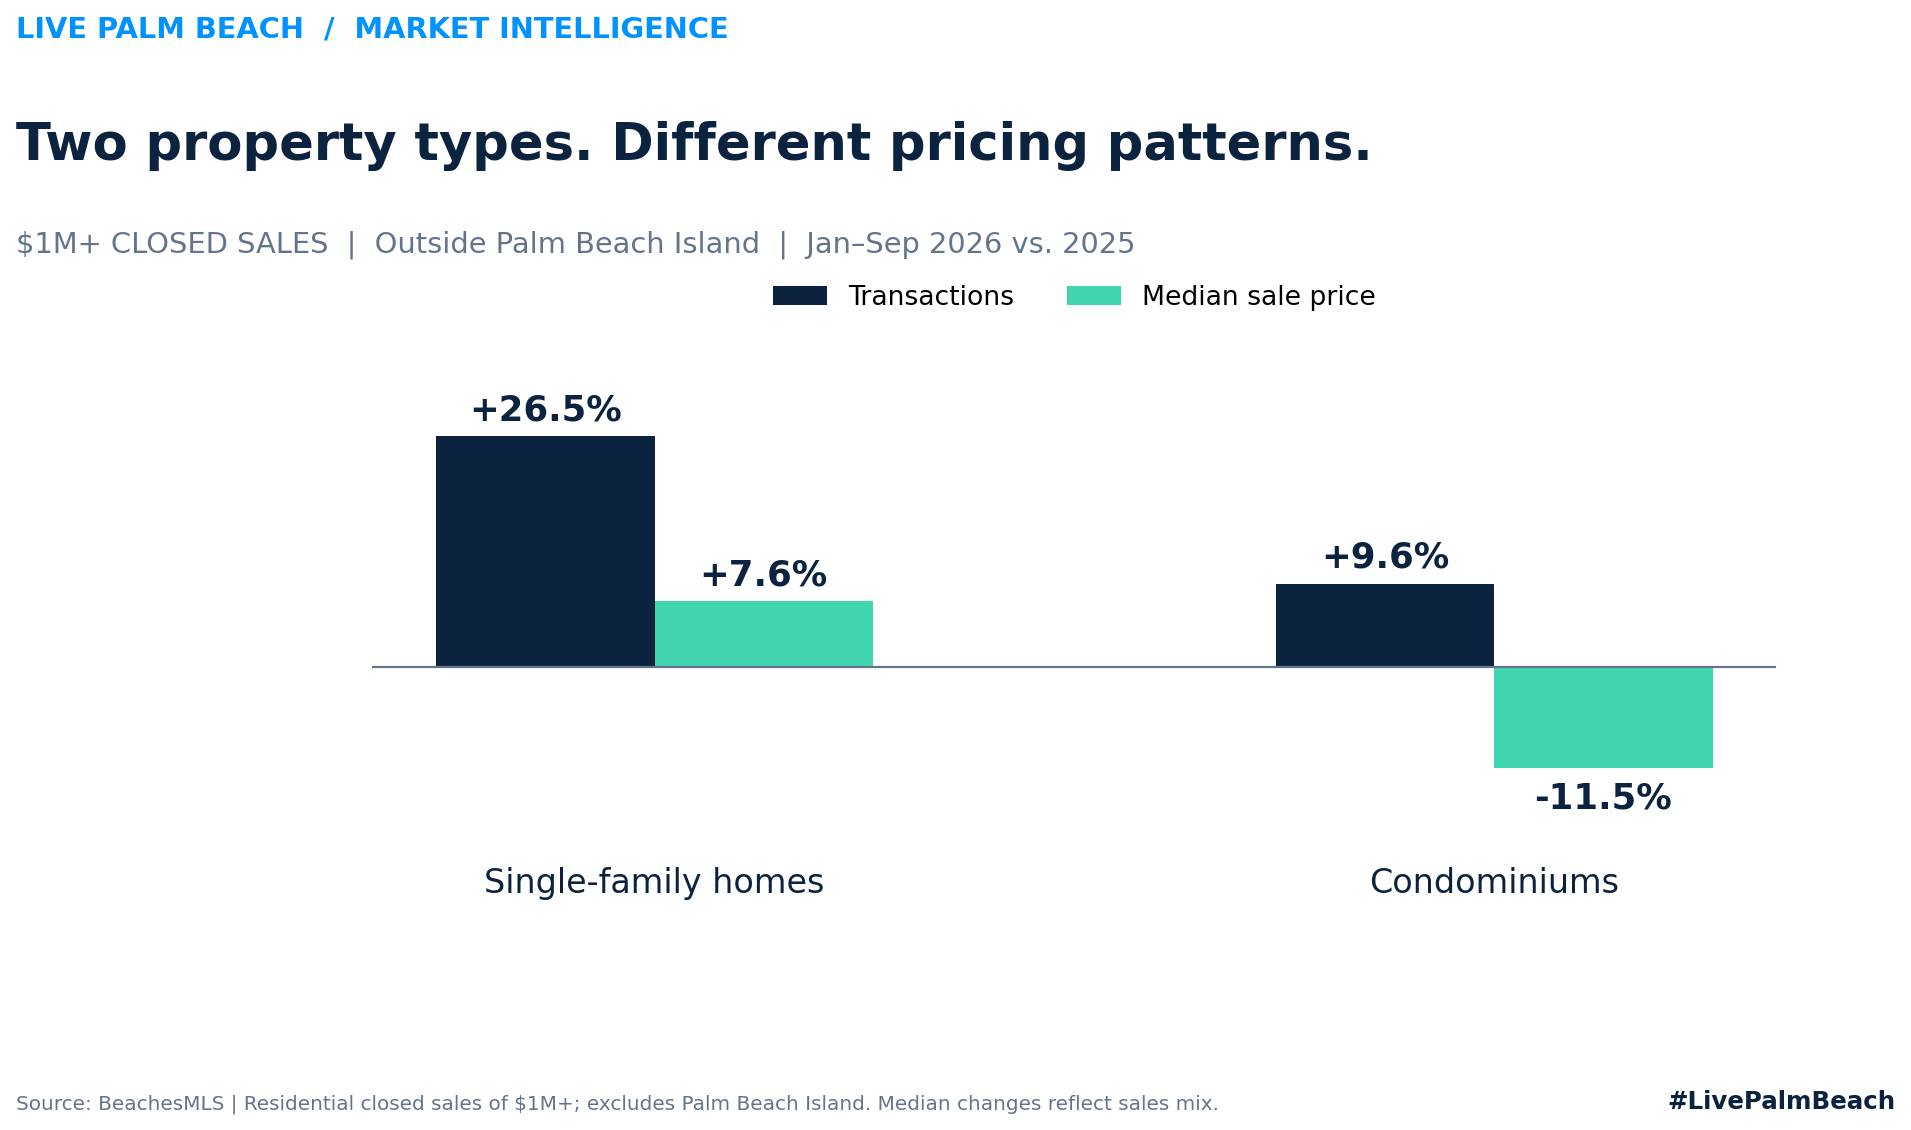
Year-to-date results tell a similar story. Through September, single-family transactions increased 26.5%, from 2,622 to 3,316 sales. The median price rose 7.6%, from $1.65 million to $1.775 million.
What stands out is the combination of higher transaction volume and increased activity in the upper-luxury price ranges.
The $5 million to $10 million market includes newly constructed residences, private club estates, and waterfront properties in established communities. These are distinct markets, and their performance cannot be evaluated through countywide averages alone.
For buyers and sellers operating at this level, understanding the competitive inventory within a particular community remains essential.
Geographic Market Highlights
Palm Beach County's luxury market is best understood as a collection of distinct communities. The year-to-date sales data reveals important differences in both the pace and composition of activity.
Palm Beach Gardens
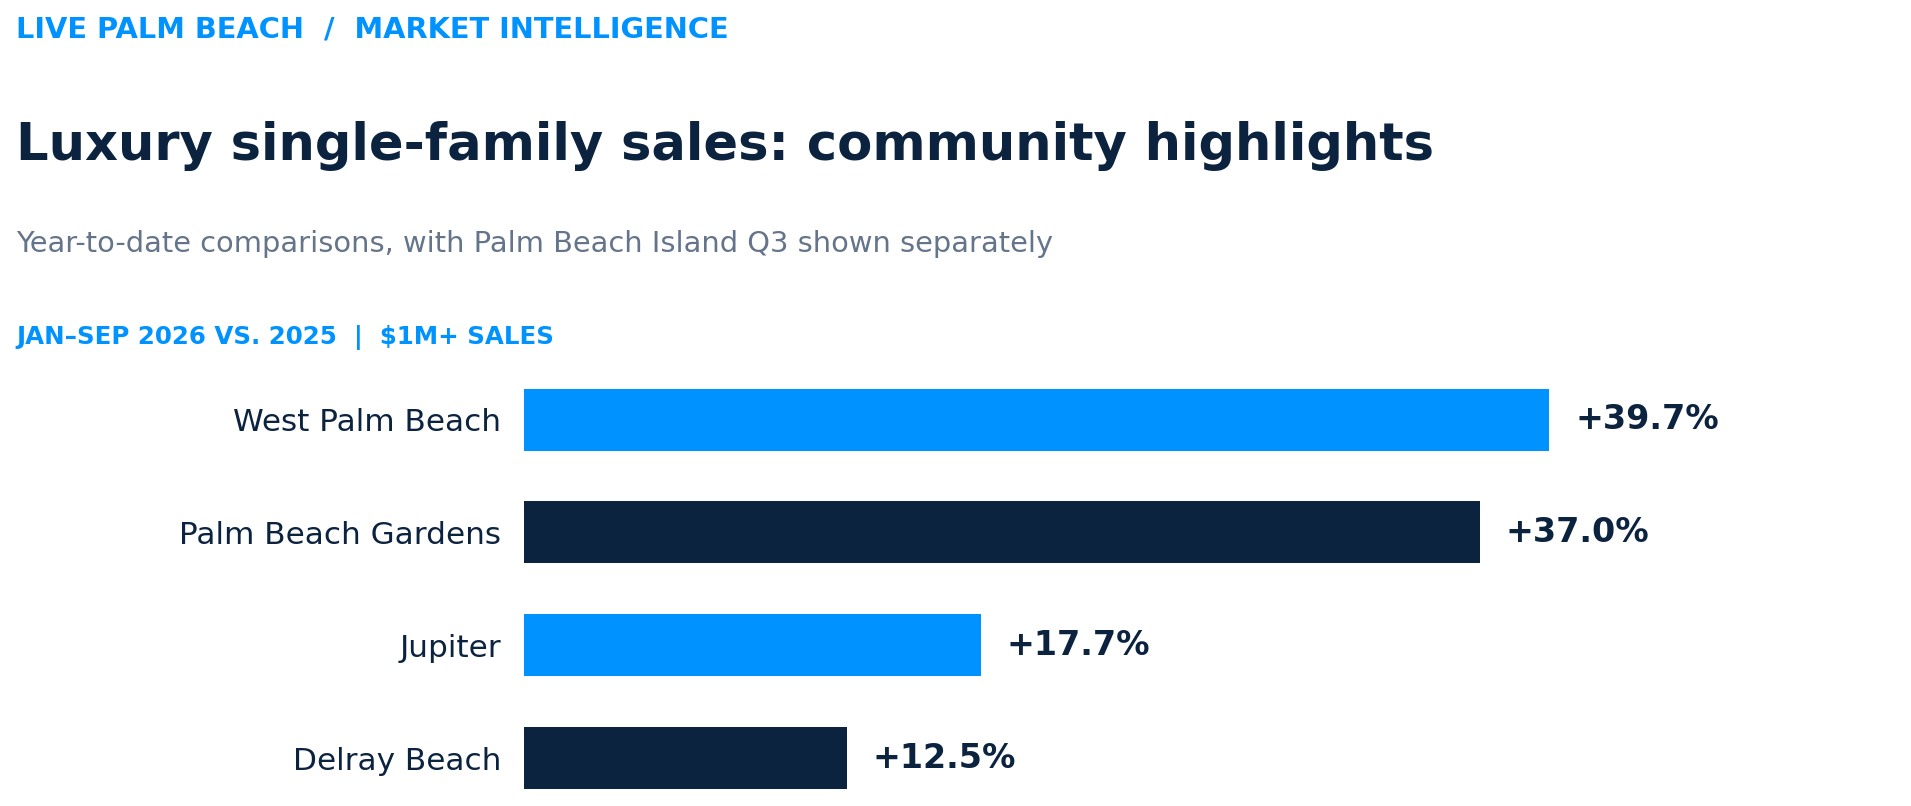
Single-family transactions of $1 million or more increased 37%, from 400 to 548 sales.
Palm Beach Gardens recorded one of the strongest increases among the communities analyzed. Its range of established private club neighborhoods, newer luxury developments, and larger single-family properties provides buyers with alternatives across several price points.
The breadth of that housing stock makes community-level comparisons particularly important when evaluating property values.
Jupiter
Jupiter's single-family luxury transactions increased 17.7%, from 322 to 379 sales. Third-quarter residential transactions across property types rose approximately 37%.
Jupiter encompasses several distinctly different luxury markets, including waterfront estates, golf communities, and newer gated developments. The increase in activity is encouraging, but individual neighborhoods can experience very different pricing and inventory conditions.
West Palm Beach
West Palm Beach recorded substantial growth in both single-family and condominium transactions.
Single-family sales increased 39.7%, from 229 to 320, while condominium transactions rose from 56 to 96 during the first nine months of 2026.
What makes West Palm Beach particularly interesting is the increase across two different residential markets. Established single-family neighborhoods and luxury condominium developments serve different buyers, yet both experienced considerably more transaction activity.
North Palm Beach
North Palm Beach's single-family luxury market was relatively stable, with 57 sales compared with 59 a year earlier.
Condominium transactions, however, increased from 20 to 32.
This contrast is a useful reminder that increased activity in one property category does not necessarily extend to another, even within the same community.
Delray Beach
Single-family luxury transactions increased 12.5%, from 368 to 414 sales, while condominium transactions rose from 41 to 65.
Interestingly, third-quarter residential sales were unchanged year over year. The stronger year-to-date performance therefore reflects gains earlier in 2026 rather than continued acceleration during the summer quarter.
Palm Beach Island
Palm Beach Island continued to distinguish itself at the highest end of the market.
Third-quarter single-family transactions more than doubled, increasing from 13 to 27 sales. The median sale price reached $12 million, up 6% year over year.
Through September, 131 single-family properties had sold for approximately $2.3 billion, already exceeding the Island's full-year 2025 transaction and dollar volume.
I examine the Island's market in greater detail in my separate report, Q3 2026 Palm Beach Island Market Update: Broader Activity. Tighter Supply.
The Luxury Condominium Market: More Transactions, A Different Pricing Story
Luxury condominium activity increased during the third quarter, although pricing results differed from the single-family market.
Outside Palm Beach Island, condominium sales of $1 million or more increased 14.3%, from 126 to 144 transactions. The median sale price was essentially unchanged at approximately $1.79 million.
For the first nine months of 2026, transactions increased 9.6%, from 591 to 648 sales. The year-to-date median declined 11.5%, from $1.92 million to $1.7 million.
The combination of increased sales and a lower year-to-date median reflects a different mix of properties sold. It should not be interpreted as an equivalent decline in the value of comparable residences.
Not All Condominium Markets Are Alike
Luxury condominium performance varies considerably by location, building age, condition, and financial strength. Year-to-date transactions increased in West Palm Beach, Jupiter, North Palm Beach, and Delray Beach, while Palm Beach Gardens experienced a modest decline. For buyers, understanding building reserves, insurance costs, and potential assessments remains as important as evaluating the residence itself.
What the Market Means for Buyers and Sellers
The increase in luxury transactions is encouraging, but stronger sales activity does not mean every property is performing equally.
For Buyers
More transactions indicate continued competition for desirable properties, but they do not eliminate opportunities to negotiate or the need for careful valuation.
I encourage buyers to focus on comparable sales, property condition, replacement cost, and the availability of alternatives within their preferred communities.
In the condominium market, building financials and potential future ownership costs deserve particular attention. Two residences with similar asking prices can represent very different investments.
For Sellers
Higher transaction activity creates opportunity, particularly for owners of well-located single-family homes. However, buyers remain selective, and pricing must reflect the property's condition, location, and competitive alternatives.
A successful strategy begins with understanding the market for the specific property, not simply applying a countywide percentage to its estimated value.
Thoughtful preparation, appropriate pricing, and effective positioning remain the foundation of a successful sale.
Looking Ahead: The 2026–2027 Season
Palm Beach County enters the winter selling season with considerably more luxury transaction activity than a year earlier.
The increase in single-family sales across multiple price points is particularly noteworthy, while the condominium market continues to reflect substantial differences among locations and buildings.
As the season unfolds, I will be watching three indicators: the pace of new listings, the relationship between asking prices and completed sales, and whether the increased activity in the $2 million to $10 million market continues.
The third-quarter results reinforce a principle I have long emphasized: Palm Beach County is not one luxury real estate market. Each community, property type, and price segment has its own competitive dynamics.
Understanding those distinctions is what allows buyers and sellers to make informed decisions.
Market Data & Methodology
Market statistics reflect analysis of BeachesMLS closed-sales records for residential properties sold at $1 million or more during Q3 and January–September 2025 and 2026. Detailed MLS comparisons exclude the Town of Palm Beach unless otherwise indicated. Selected coastal-area price-tier comparisons use MLS city designations and include properties throughout those communities, not exclusively waterfront residences.
Palm Beach Island statistics incorporate the previously completed Q3 2026 Palm Beach Island market report, including broker-reported transactions. The combined countywide Q3 comparison therefore draws on more than one transaction source.
Changes in median sale prices reflect the mix of properties sold and should not be interpreted as direct measures of appreciation or depreciation for comparable properties.
Nadine Fite
Luxury Real Estate Advisor | Palm Beach
917.513.9592
Compass Palm Beach
#LivePalmBeach